Talking about money with someone you love can feel weirdly intense. Not because either of you is “bad with money” or “too sensitive,” but because money is tied to safety, freedom, and old stories from how you grew up. If you have ever had a budget talk that turned into a character debate, you are not alone.
The good news: you do not need the perfect spreadsheet or one magical bank setup. You need a simple system you both understand, a fair way to split costs, and a repeatable routine for checking in. This is exactly the system I wish I had in my early twenties when I was juggling debt payments and rent anxiety and pretending I was “fine.”
Start with the real goal: teamwork
Before you open an app or move a single dollar, get on the same page about what budgeting is for.
- Budgeting is a plan, not a punishment. It is not a way for one partner to police the other.
- Fair is not always 50/50. Especially when incomes are different.
- Your relationship needs “yes” money. If the budget is only bills and restrictions, resentment can grow fast.
A quick script you can steal: “I want us to feel safe and relaxed about money. Can we build a plan that makes life easier for both of us?”
Step 1: Pick a money setup
There is no single “correct” way to combine finances. There is only what supports your relationship, your goals, and your personalities.
Option A: Fully joint
Best for: couples who are aligned on spending, have shared goals, and prefer simplicity.
Watch outs: if one partner feels monitored, small purchases can spark bigger fights. If there is controlling behavior, financial abuse, or active addiction or impulse spending, fully joint accounts may not be safe.
Option B: Fully separate
Best for: couples with very different money styles, newer relationships, or those rebuilding trust.
Watch outs: it can feel transactional if you do not also plan shared goals.
Option C: Hybrid (my favorite for many couples)
How it works: you keep personal accounts, plus one joint account for shared expenses and goals.
Why it works: shared bills are easy, and each person still has autonomy.
Simple hybrid structure:
- Joint Bills account: rent or mortgage, utilities, groceries, insurance, subscriptions you both use
- Joint Goals account: emergency fund, travel, home repairs, future baby costs, sinking funds
- Personal accounts: personal spending, hobbies, gifts, personal debt, personal savings
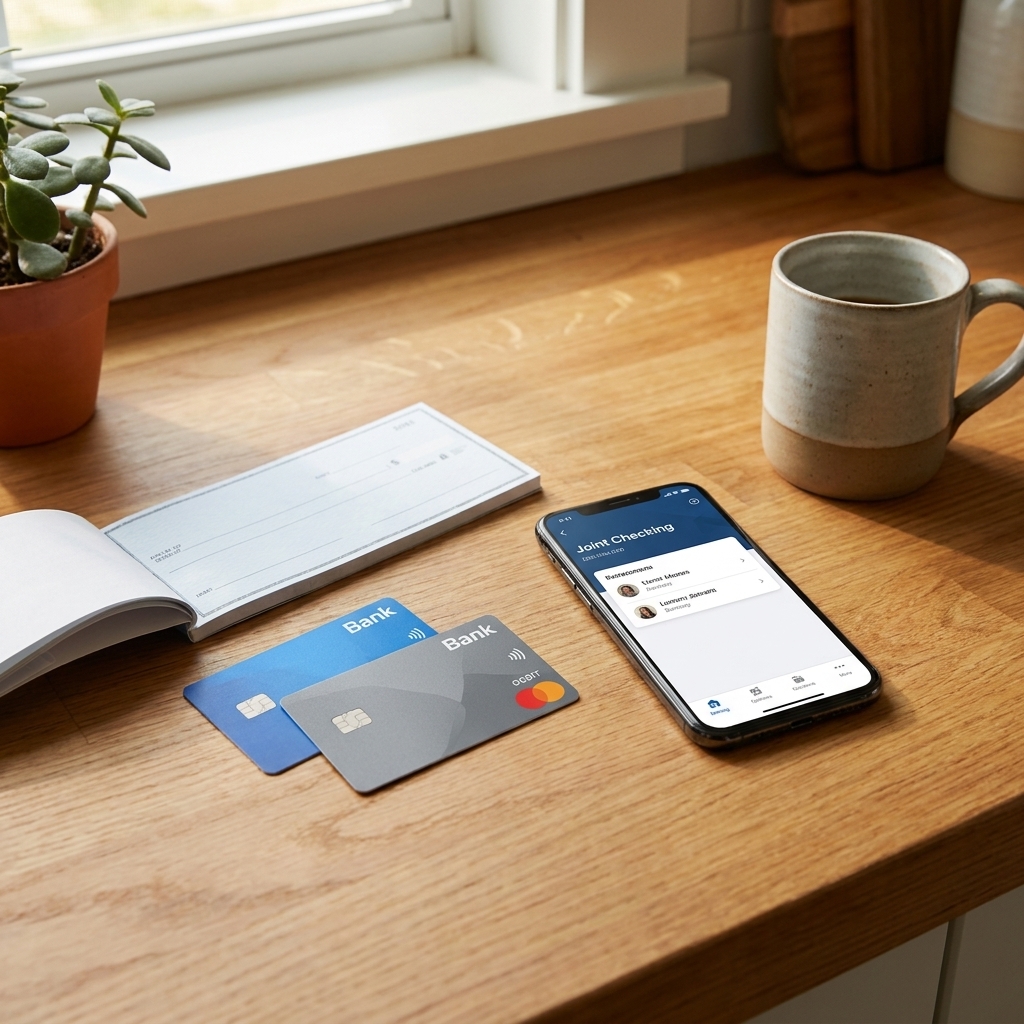
If you are moving in together, newly married, or just tired of Venmo math, a hybrid setup is often a low-stress place to start. You can always adjust later.
Quick note: Money and relationships also have legal and tax layers. Marriage and cohabitation rules vary by location, and things like shared debt, benefits, and prenups can change what makes sense. In some places, for example, community property rules can affect what is considered “shared,” and debt opened during marriage can create shared liability. This is general guidance, not legal or tax advice.
Step 2: Define shared vs personal
This one sounds obvious until you are arguing about whether takeout was a “joint expense” because you both ate it.
Use this rule: If you both benefit from it consistently, it is shared. If it is individual, optional, or uneven, it is personal unless you both agree otherwise.
Common shared expenses
- Housing (rent or mortgage)
- Utilities and internet
- Groceries and basic household supplies
- Joint transportation costs (if you share a car or insurance)
- Childcare and kid expenses
- Pet expenses
- Streaming services you both use
Common personal expenses
- Personal debt from before the relationship (often handled personally, sometimes supported as a joint goal by agreement)
- Gifts (especially gifts for each other)
- Hobbies, lunches out, personal shopping
- Solo travel or nights out
- Anything that triggers “I feel judged” energy
Pro tip: Add a small shared “relationship fun” line item for dates, takeout, and mini adventures. If you do not budget for joy, joy still happens. It just shows up as an argument.
Step 3: Split bills fairly
Many couple money fights are not really about math. They are about fairness, pressure, and whether both people can breathe. Here are three clean methods.
Method 1: 50/50 split
Best when: incomes are similar and both partners feel good about it.
Method 2: Income-based split
How it works: each partner contributes to shared expenses in proportion to their income.
Example: Partner A earns $4,000 a month and Partner B earns $2,000 a month. Total is $6,000.
- Partner A pays 67% of shared costs.
- Partner B pays 33% of shared costs.
For some couples, this can reduce resentment because it helps keep lifestyle costs from crushing the lower earner.
Method 3: Assign bills
How it works: one partner covers specific bills, the other covers the rest, aiming for a fair balance.
Watch outs: this gets messy if bills change or one partner quietly takes on more.
A quick fairness check
After you choose a split, ask:
- Does either of us feel stretched thin every month?
- Do we both have some personal spending money left?
- If one of us lost income temporarily, would we know what to do?
If one partner is always stressed and the other is comfortable, you probably do not have a willpower problem. You have a systems problem. Adjust the split.
Step 4: Build a budget
You do not need an elaborate setup. Start with four buckets, then get more detailed only if you want to.
The four-bucket couple budget
- Shared fixed bills: rent or mortgage, insurance, internet, daycare
- Shared variable spending: groceries, gas, household items, dining out
- Shared goals: emergency fund, travel, sinking funds
- Personal money: each partner gets an agreed amount with no commentary
Do not forget sinking funds
Sinking funds are mini savings buckets for predictable, non-monthly expenses. They can prevent the “How did we spend $900 this month?” feeling.
- Car repairs and maintenance
- Medical and dental
- Holidays and gifts
- Annual subscriptions
- Home maintenance
- Pet vet visits
Easy way to set sinking funds: take the expected yearly cost and divide by 12. Set that amount aside monthly.
Plan for transitions
If you are moving in together or combining households, do not let one-time costs ambush you. Consider a short-term “setup fund” for things like deposits, movers, furniture, kitchen basics, and switching or merging plans (insurance, phone, internet).
Coordinate retirement
Retirement is one of those categories that can quietly drift if you never name it. A simple approach many couples use is: get any employer match first, then agree on a shared target (for example, both partners contributing a similar percentage of income), and revisit it as incomes change.
Credit card basics for couples
If you use credit cards for shared spending, decide upfront what “shared” goes on which card, and who is responsible for paying it. A joint card can simplify tracking, but only if you can pay the balance in full each month. Interest turns “convenience” into a long, expensive argument.
A quick goals check
If you are deciding between “save for emergencies” and “invest for the future,” a simple rule is: cover near-term stability first. Many couples aim for an emergency fund of 3 to 6 months of shared essential expenses, then ramp up long-term goals like retirement contributions, especially if there is an employer match.
Step 5: Automate it
If your system requires weekly heroics, it will eventually fail. Automation helps you avoid re-living the same money argument every month.
- Direct deposit split (if available): automatically send each paycheck portion to the joint bills account and joint goals account.
- If your employer cannot split deposits: set an automatic transfer for the day after payday.
- Autopay shared bills: at least the minimums, ideally the full amount.
- Auto-transfer to goals: emergency fund and sinking funds should happen without a debate.
Automation is not about being rigid. It is about reducing decision fatigue so you can save your energy for things that matter.
Step 6: Hold a monthly meeting
This is the skill that changes everything. A good budget meeting is short, predictable, and focused on decisions, not blame.
Set the vibe first
- Pick a consistent time: first Sunday, last day of the month, whatever you can keep.
- Keep it to 30 to 45 minutes: in my experience, long meetings are where “logistics” turns into tension.
- Pair it with something pleasant: coffee, a walk, or takeout.
The 20-minute agenda (steal this)
- Wins (2 minutes): one money win each. Even “we paid rent on time” counts.
- Reality check (5 minutes): look at the last month’s spending without commentary like “why did you…” Focus on totals.
- Upcoming month (8 minutes): list known expenses and events. Travel, birthdays, car registration, school costs.
- Decisions (5 minutes): set spending limits for groceries, dining out, and fun. Confirm how much goes to goals.
Rules that prevent most fights
- No surprise interrogations. If something looks off, ask “Can we talk about what happened here?” not “What is this?”
- Use numbers, not labels. Say “We spent $180 on dining out” instead of “We were irresponsible.”
- One person is the bookkeeper, both are the decision makers. If one partner tracks, that does not mean they get final say.
- Park big emotional topics. If it turns into an argument, pause and schedule a separate conversation.
If you have tried budget talks before and they went badly, start smaller: 10 minutes, one topic, and end on purpose.
How to handle sticky stuff
Different incomes
Many couples do well with an income-based split for shared expenses, then making sure both partners have personal money. The lower earner should not need to ask permission to buy lunch with friends.
Different spending styles
You are not enemies. You are two nervous systems trying to feel safe.
- Savers often need predictability.
- Spenders often need flexibility and room to enjoy life.
A helpful compromise: agree on a guilt-free personal spending amount, and require a quick joint yes for anything above a set threshold (for example, $150).
Debt brought into the relationship
There is no one rule here. What matters is clarity and consent.
- Personal responsibility model: each person pays their own pre-relationship debt.
- Team payoff model: you treat debt as a shared goal and attack it together.
- Hybrid: one partner pays their debt, the other supports indirectly by covering more shared expenses for a season.
Whichever you choose, put it in writing as a plan. Debt creates tension when it is vague.
Secret spending or money shame
If either of you is hiding purchases, the fix is not stricter rules. The fix is rebuilding safety.
Start with: “I want us to feel like a team. Can we set up a system where you can spend without fear and we still protect our goals?”
If secrecy is ongoing or tied to trust issues, consider a couples therapist. Money fights are often trust fights in a budget costume.
When fully joint is not a good idea
If either partner has a pattern of controlling money, gambling, addiction, or financial infidelity, pause before combining everything. Keeping accounts separate, setting clear boundaries, and getting professional support can be the healthiest move.
A simple budget example
Here is what a basic hybrid setup could look like, using round numbers.
Example assumes: $4,600 total monthly take-home income combined.
| Category | Monthly Amount | Where it goes |
|---|---|---|
| Shared fixed bills | $2,800 | Joint bills account |
| Shared variable spending | $850 | Joint bills account |
| Emergency fund | $250 | Joint goals account |
| Sinking funds | $200 | Joint goals account |
| Relationship fun | $200 | Joint bills account |
| Personal spending | $300 total ($150 each) | Personal accounts |
Total planned: $4,600. If your total is higher than take-home in your household, the fix is not shame. It is adjusting categories until the plan fits your real numbers.
This is not about perfection. It is about knowing what money is for before it disappears.
Couple budgeting FAQ
Should couples combine bank accounts?
Only if it reduces stress, not increases it. Many couples do best with a hybrid system: one joint account for shared expenses plus personal accounts for independence.
How do we split bills if one of us makes more?
An income-based split is often a fair starting point. It helps many couples keep breathing room and can prevent lifestyle costs from landing mostly on the lower earner.
How much personal spending money should we each get?
Pick an amount you can sustain monthly and that prevents nitpicking. Even $50 to $200 each can lower tension because it protects autonomy.
What if one partner refuses to budget?
Start tiny. Ask for one 15-minute check-in to cover only shared bills and upcoming expenses. Sometimes “budget” feels like judgment, but “plan for rent and groceries” feels like teamwork.
How do we budget when income is irregular?
Use a baseline budget built on your lower, more reliable income. If you can, build a buffer, such as keeping one month of shared essential expenses as a cushion in the joint bills account or a separate savings account. When extra money comes in, decide in advance where it goes, such as a percentage to bills, goals, and personal spending.
Your next steps
- Tonight: Agree on joint vs separate vs hybrid and define shared expenses.
- This week: Set up the joint account(s) if needed and decide on a fair split.
- This month: Hold one budget meeting with the 20-minute agenda and write down your decisions.
If budgeting as a couple has been painful before, that does not mean you are incompatible. It usually means you did not have a system yet. Systems lower the temperature so love can do its job.
And if you want the most important reminder taped to your fridge: It is not you vs your partner. It is both of you vs the problem.