If you are juggling multiple credit card bills and feel like your payments are mostly feeding interest, a Debt Management Plan (DMP) can be a real, practical middle path between “I will just try harder” and “I guess I have to file bankruptcy.”
A DMP is not a loan. It is a structured repayment plan set up by a credit counseling agency, often a non-profit. The agency works with your credit card companies to request lower interest rates, sometimes ask for certain fees to be waived, and then combine your payments into one monthly payment you make to the agency. The agency distributes that payment to your creditors.
Important: creditor concessions are not guaranteed. The details (rates, fees, which accounts qualify) vary by creditor and by your situation.
What a Debt Management Plan is (and is not)
What it is
- A repayment plan for unsecured debts, most commonly credit cards.
- Set up through a credit counseling agency, often non-profit. (Some for-profit companies also offer similar programs, so verify who you are working with.)
- Designed to lower interest so your payments start making a real dent in the balance.
- One monthly payment to the agency, which pays your creditors for you.
- A defined payoff timeline, commonly around 3 to 5 years, depending on what you owe and what you can afford.
What it is not
- Not debt settlement (where you stop paying and try to negotiate a lump-sum payoff for less). DMPs are about paying your debt back in full, usually with better terms.
- Not a consolidation loan. You are not borrowing new money to pay off old money.
- Not a quick fix. It is a steady, routine plan that works because the math finally starts working for you.
How DMPs work, step by step
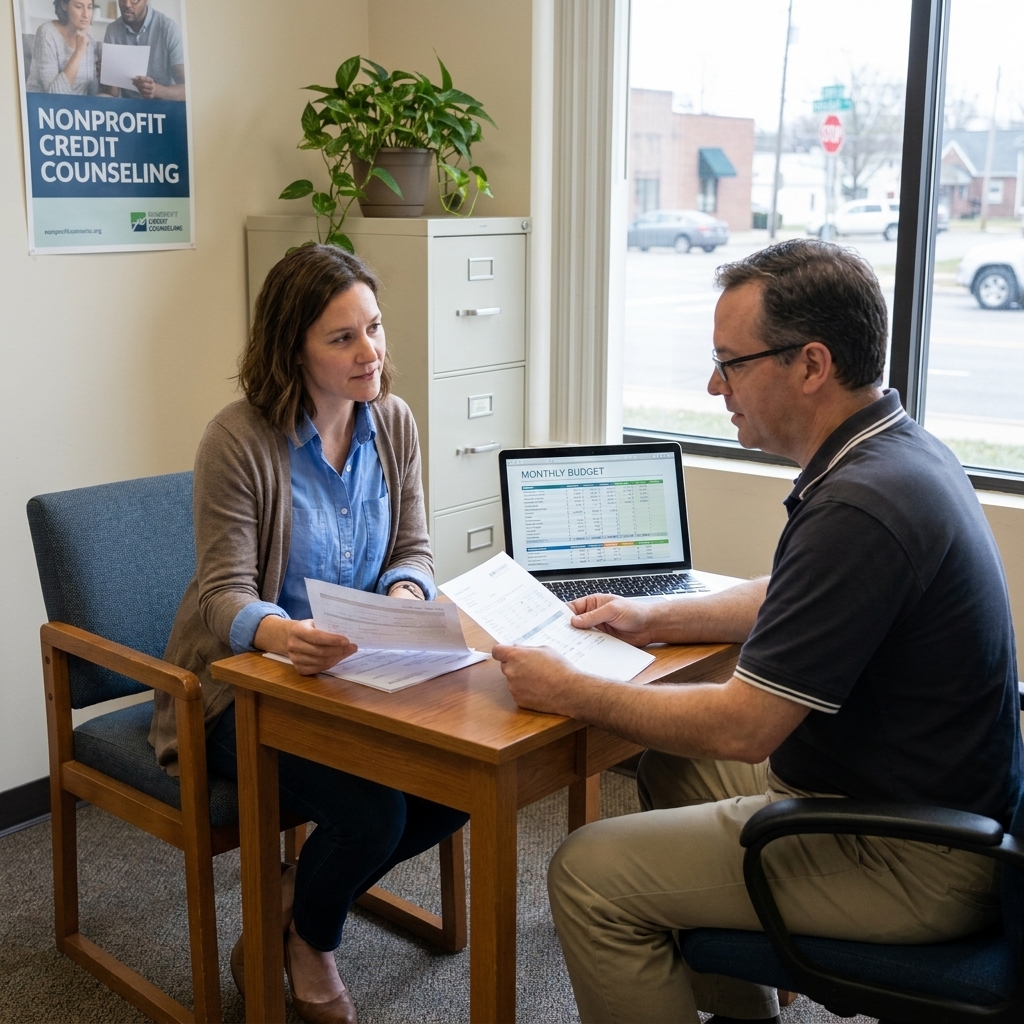
1) You meet with a certified credit counselor
This usually starts with a review of your income, expenses, and debts. A good counselor will help you build a realistic budget first. If a DMP is not the best option, they should say so.
2) The agency proposes a plan and contacts your creditors
If a DMP fits, the agency will outline a proposed monthly payment and reach out to your credit card companies to request concessions such as:
- Lower APRs (sometimes dramatically)
- Re-aging some past-due accounts (when available). This is creditor-specific and may require a certain number of on-time payments first.
- Waiving certain fees or stopping certain fees from being assessed going forward (varies widely by creditor)
Creditors are not required to agree, but many major issuers regularly participate.
3) You close or stop using enrolled credit cards
This is one of the biggest tradeoffs. In many DMPs, you will be asked to close the accounts or agree not to use them while you are in the plan. That is part of why creditors may offer lower rates: the debt stops growing. It can also mean you temporarily lose access to balance transfers or promotional APR offers on those cards.
4) You make one monthly payment to the agency
The payment is typically due on the same day each month. The agency then sends payments to each creditor according to the plan.
5) The first 30 to 60 days can feel a little messy
Here is a detail that helps people breathe: it can take time for every creditor to process and apply the new terms. You may be making your first payment to the agency while a creditor is still updating your account on their end. During that window, you could still see a statement that looks “normal,” or even get a late notice if an account was already behind.
Do not ignore it. Stay in touch with the agency, keep records, and open your mail. The goal is to get everything current and stable as fast as possible.
6) You stay the course until the debt is paid off
If you stick with the payment schedule, you finish with a zero balance, and you did it without taking on a new loan.
What debts a DMP can help with (and what it cannot)
Usually eligible
- Credit cards
- Store cards
Sometimes possible
- Some unsecured personal loans (depends on the lender and the agency)
- Medical bills are often handled outside a formal DMP, but many agencies can still help you budget and negotiate a separate payment plan
Usually not eligible
- Mortgages
- Auto loans
- Federal student loans (these have their own programs)
- Tax debt (the IRS offers separate payment options)
- Child support or alimony
If your biggest financial fire is behind on rent or mortgage, a DMP might not be the right first move. You may need a housing counselor or a different type of hardship plan.
What you will need to get started
You do not need a perfect spreadsheet. You do need real numbers. Most agencies will ask for some combination of:
- Recent pay stubs or proof of income
- A list of monthly bills (rent, utilities, insurance, car payment)
- Credit card statements showing balances, minimum payments, and APRs
- A rough breakdown of spending (groceries, gas, childcare, subscriptions)
This part can feel vulnerable, but it is where the plan becomes realistic instead of aspirational.
How much a DMP costs
Credit counseling agencies commonly charge two types of fees:
- Set-up fee: often a one-time fee to start the plan.
- Monthly maintenance fee: a smaller ongoing fee for managing and distributing payments.
Fees vary by agency and by state. A reputable agency will tell you the fees up front, in writing, before you sign anything. If you are truly in a pinch, ask whether they can reduce or waive fees.
One important way to think about cost: if the DMP lowers your interest rate enough, your total payoff cost (and payoff timeline) can improve even after fees. The counselor should be able to show you the numbers.
The real pros and cons
Pros
- Lower interest can mean you pay off debt faster and save a lot of money.
- One payment is simpler than tracking multiple due dates.
- Clear finish line with an actual plan you can follow.
- Built-in accountability without having to “white-knuckle” it alone.
- Less extreme than bankruptcy, and you repay the principal.
Cons
- Accounts may be closed or frozen, which can temporarily affect your credit utilization and average age of accounts.
- You cannot keep using credit the way you used to, at least for enrolled accounts.
- Missing a payment can jeopardize the plan. You could lose creditor concessions, and in some cases you may be removed from the program.
- Not all creditors participate, so you might still have a bill or two outside the plan.
- It requires stable cash flow. If your income is unpredictable, a DMP can be harder to maintain.
Kitchen table truth: A DMP works best when you can make a consistent monthly payment, but your interest rates are the thing keeping you stuck.
Will a DMP hurt your credit?
“Hurt” is a strong word, but a DMP can cause short-term credit score movement, and it can affect how lenders interpret your credit report.
What can happen
- Closed or frozen accounts can raise utilization (because you have less available credit), which can lower your score temporarily.
- On-time payments help. The biggest long-term driver is paying consistently, and a DMP is designed to make that doable.
- Credit reporting notes can appear. Some creditors may code or note the account as managed through credit counseling, and accounts may also be reported as closed by the consumer or creditor depending on the issuer. The scoring impact is usually indirect, but lenders may still notice the context.
If your score is already taking hits from high utilization, late payments, or maxed-out cards, many people find a DMP is a net positive over time because it helps them get current and stay current.
DMP vs. debt settlement vs. consolidation
| Option | How it works | Best for | Big watch-outs |
|---|---|---|---|
| Debt Management Plan (DMP) | You repay in full with reduced rates through a credit counseling agency | People who can afford a monthly payment but need interest relief | Cards often closed or frozen, must stay consistent |
| Debt settlement | You try to pay less than owed, often after stopping payments | Severe hardship where full repayment is unrealistic | Credit damage, fees, collections risk, possible taxes on forgiven debt (exceptions can apply, including insolvency) |
| Consolidation loan | You take a new loan to pay off cards, leaving one loan payment | Good credit and stable income, can get a lower rate | Fees, temptation to run cards back up |
How to find a reputable agency
You do not need to guess. Reputable credit counseling tends to look boring in the best way: clear disclosures, patient explanations, no pressure tactics.
Green flags
- They offer a budget and education session before pushing a DMP.
- Fees are clearly explained up front.
- They send written details of the plan, including payment schedule.
- They are willing to explain alternatives if a DMP is not the best fit.
Red flags
- Promises like “we can erase your debt” or “guaranteed results.”
- Pressure to sign immediately.
- They will not tell you fees until after you enroll.
- They tell you to stop paying your creditors as a strategy (that is more aligned with settlement, not a DMP).
Two well-known U.S. trade groups in this space are the National Foundation for Credit Counseling (NFCC) and the Financial Counseling Association of America (FCAA). Membership is not a magic stamp, but it is a useful starting filter.
If you are in the U.S. and you want extra peace of mind, you can also:
- Ask whether the organization is a 501(c)(3) non-profit (if they claim to be), and verify it through IRS resources
- Check your state consumer protection office or state attorney general for complaint history
- Search the CFPB complaint database for patterns tied to the company name
What it feels like month to month
Here is the reality most people do not say out loud: the first month can feel scary because you are handing the process to someone else and agreeing to tighter boundaries.
Then, it usually gets quieter.
- You have one due date to remember.
- You are not watching balances jump from interest as aggressively.
- You have a plan that is written down, not just hope.
If you are used to “floating” expenses on credit cards, you will need a cash flow system while you are in the DMP. For many people, that means:
- Using a debit card or cash for day-to-day spending
- Building a small starter emergency fund, even $500 to $1,000
- Automating bills so you do not rely on memory when life gets busy
Who a DMP is best for
A DMP tends to work well when:
- You have mostly high-interest credit card debt.
- You can afford a monthly payment, but the interest is keeping you stuck.
- You are ready to stop using credit while you clean this up.
- You want a structured path and a finish line.
It might not be the best fit if you are dealing with:
- Very low income with no wiggle room
- Debt types a DMP cannot address (like most student loans)
- An urgent need for legal protection from collections or lawsuits (talk to a qualified bankruptcy attorney if that is on the table)
Questions to ask before you sign
- Which of my creditors will be included, and which will not?
- What interest rates are you expecting each creditor to offer, and are they guaranteed?
- Are my accounts being closed or frozen?
- What is the total monthly payment, including fees?
- When will the first payment be due, and how long does it take for creditors to update my accounts?
- What happens if I miss a payment?
- Can I leave the plan early, and are there any penalties?
- How will payments be disbursed and when?
If they cannot answer these clearly, keep shopping. You are allowed to be picky. This is your money and your peace.
Quick FAQ
How long does a Debt Management Plan take?
Many DMPs are designed to be completed in a few years, often around 3 to 5 years, depending on your balance and your monthly payment.
Can I keep one credit card for emergencies?
Sometimes, but it depends on the agency and the creditor. Many plans require enrolled accounts to be closed or not used. If you need an “emergency buffer,” talk through alternatives like a small starter emergency fund.
Will creditors stop calling?
Once accounts are current and payments are flowing through the plan, calls often decrease. If you are delinquent when you enroll, it can take a bit for everything to settle. Keep records and communicate in writing when possible.
Is a DMP the same as bankruptcy?
No. A DMP is a voluntary repayment program. Bankruptcy is a legal process with court involvement and specific protections and consequences.
Can I do this without a DMP?
Yes. You can DIY a payoff plan using methods like the debt snowball or avalanche. A DMP is most useful when interest rates are the obstacle and you want help negotiating and simplifying payments.
The bottom line
If you are doing “all the right things” and still watching interest eat your progress, a Debt Management Plan can turn the volume down on your finances. It is not magic. It is math, structure, and consistency.
And if you are carrying shame about needing help, please hear me: getting support is not a moral failure. It is a strategy. The goal is not to prove you can suffer through it alone. The goal is to get free.