If you are using credit cards for groceries, gas, and random Tuesday life stuff, you are not “bad with money.” You are under-resourced in the moment. I lived in that exact loop for years: paycheck hits, bills clear, one surprise pops up, and the card becomes the bridge.
The goal is not to swear off credit cards forever or shame yourself into never needing help. The goal is to stop depending on them for daily expenses while you aggressively pay down old balances.
This is the approach that helped me climb out of $45,000 of debt in my own life: make non-credit spending easier than credit, build a tiny buffer fast, and put guardrails around the moments you are most likely to swipe.
First: check your payoff plan
One of the biggest reasons people keep relying on credit cards while paying them off is simple math: the payoff plan is too aggressive for the life they are actually living.
If you are throwing every spare dollar at debt but you have no cushion for a higher-than-usual electric bill, a kid’s field trip, or a prescription refill, the card becomes your emergency fund. That is not a willpower problem. That is a plan problem.
Do this quick check
- Are you paying more than the minimums? Great. Now make sure you can do it consistently.
- Are you using the card again every month? That is a sign your monthly budget has no breathing room or your categories are underfunded.
- Is your checking account hitting near-zero before payday? You need a small buffer before you push harder on extra payments.
It is okay to temporarily lower extra payments while you build a starter buffer. It is not quitting. It is stabilizing.
Build a no-swipe buffer
You do not need a fully funded emergency fund to stop relying on credit cards. You need a small, boring cash buffer that keeps you from reaching for plastic when life wiggles.
A simple starter buffer target
- $300 to $500 if your expenses are fairly stable
- $500 to $1,000 if your income fluctuates or you have kids, a car, or medical expenses
Where to keep it: a separate savings account (or a separate “buffer” bucket if your bank has vaults). You want it close enough to access, but separate enough that you do not spend it on takeout.
How to build it fast
- Pause extra debt payments for 1 to 2 paychecks and redirect that amount to the buffer
- Sell a few unused items and send that money to the buffer first (not the card)
- Cut one category temporarily (not forever): dining out, subscriptions, or convenience spending
Once the buffer exists, you can go back to aggressive payoff with less backsliding.
Some people prefer building a larger emergency fund before pushing debt payoff hard. This is a starter-buffer approach designed to reduce new swipes while you keep paying minimums and stay steady.
Switch to non-credit spending
Most of us do not rely on credit cards because we love interest. We rely on them because they are frictionless: tap, done, later-me deals with it.
Your job is to make non-credit spending the default setting, meaning debit, cash, or a prepaid-style account you load on purpose.
Try one setup (pick one)
Option A: Debit-only week for variable spending
Use your debit card for groceries, gas, and household needs for one week. Before the week starts, transfer a set amount into checking that covers those categories. When it is gone, you pause spending.
If debit makes you nervous, that is fair. Consider using a separate checking account that you keep at a low balance and transfer into weekly. It limits damage if your card details get compromised.
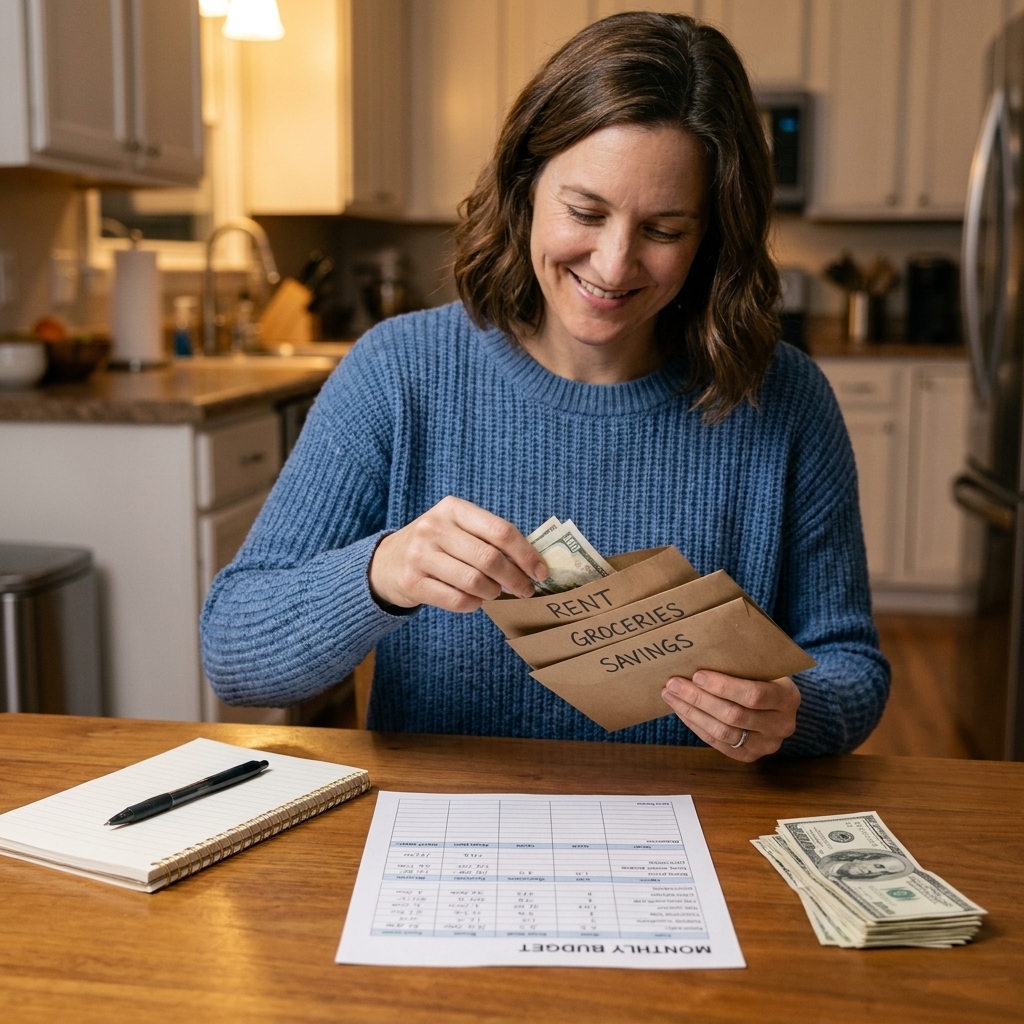
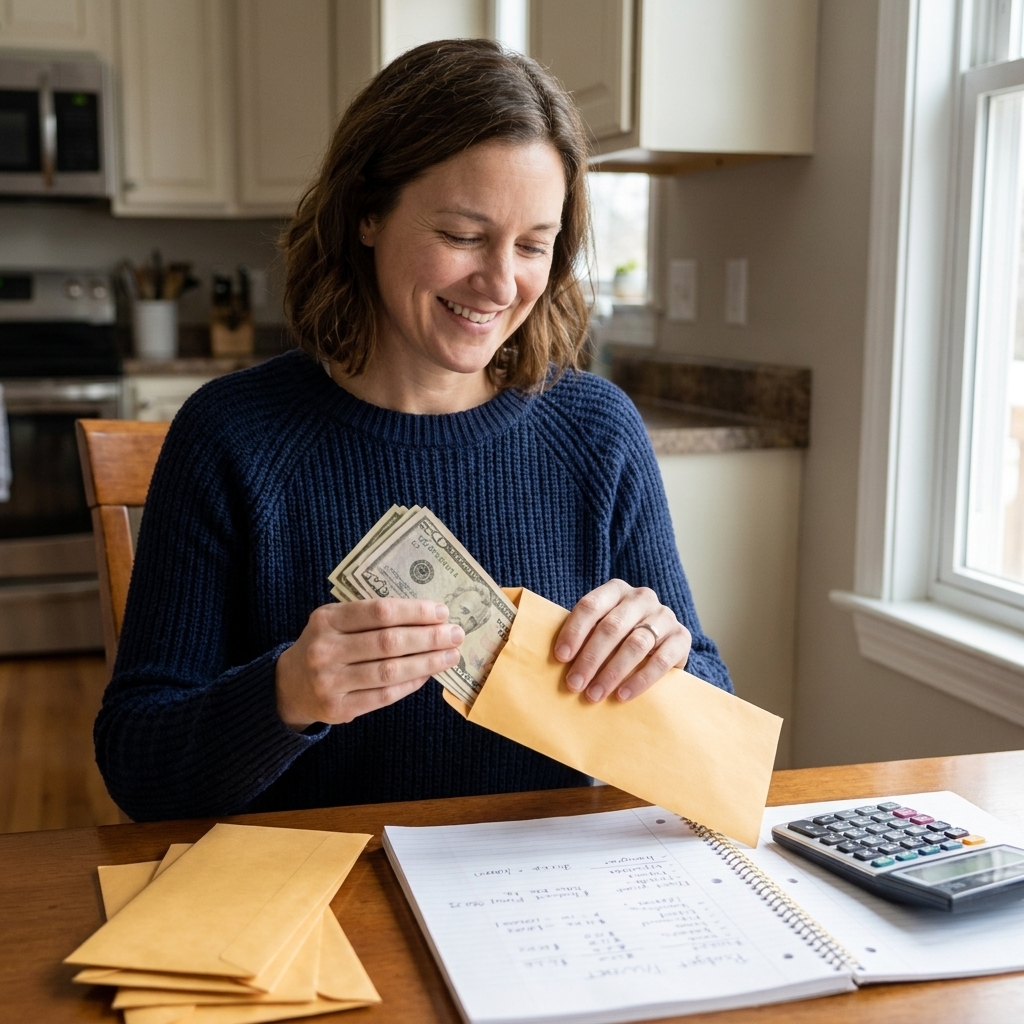
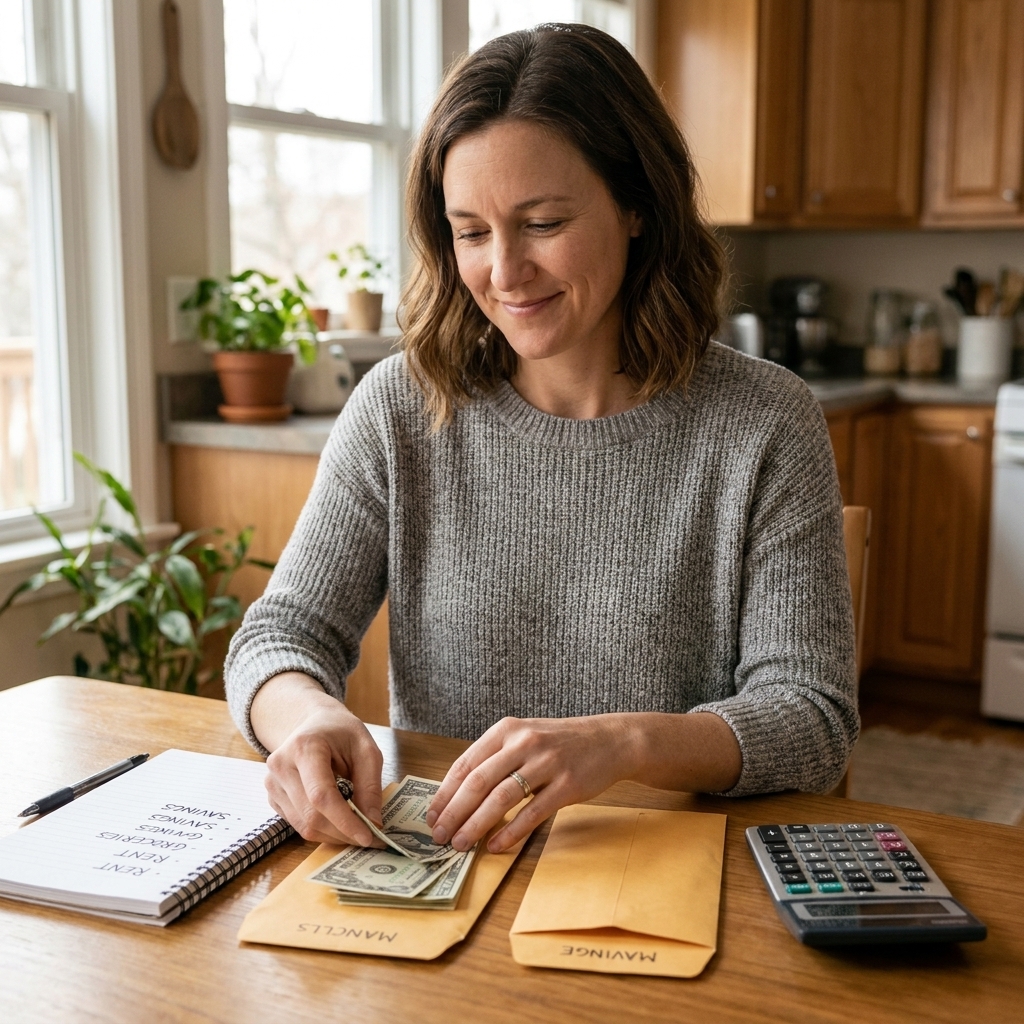
Option B: Cash envelopes for trouble categories
If you tend to overspend on food, errands, or “little treats,” pull cash for those categories only. Cash forces a pause and makes tradeoffs visible.
Option C: One-card quarantine
If you have multiple cards, pick the one with the lowest interest (or the one you are targeting last) and lock the rest down. Fewer cards equals fewer “maybe I will just…” moments.
Use a cash-first order
When money is tight, order matters. Here is the sequence I teach because it reduces credit card dependence without letting debt get ignored.
Pay in this order after each paycheck
- Keep the lights on: rent or mortgage, utilities, minimum transportation, basic groceries
- Minimums on all debts: every card, every loan (protects your credit and stops fees)
- Buffer contribution: until you hit your starter target
- Extra debt payment: to your chosen payoff target
If you do not have enough for step 2, that is a bigger problem than “using credit cards too much.” Call lenders, ask about hardship plans, and prioritize housing and essentials.
Stop the payment-then-swipe trap
This is sneaky: you make a payment, your available credit goes up, and your brain reads that as permission. It feels like progress, so swiping does not feel like backtracking.
Set a bright line rule
- Rule: “Credit cards are not for daily spending while I am in payoff mode.”
- Exception: one truly necessary category if needed, and only if you have cash set aside to pay it off right away.
Add speed bumps
- Remove saved cards from online stores and delivery apps
- Log out of shopping apps and delete one-click pay options
- Keep your physical card out of your wallet (drawer, envelope, or locked box)
- Remove the card from your digital wallet if you use tap-to-pay
Friction is your friend. You are not trying to be “strong.” You are trying to make the better choice the easier choice.
If you must use a card
Sometimes, a card is genuinely the least-bad option in the short term. If your car needs a repair so you can get to work, you may need to charge it. The key is to stop the charge from becoming long-term revolving debt.
The charge-with-cash-waiting rule
Only charge an expense if you already have the cash set aside to pay it off before you get charged interest on it.
Two dates matter:
- Statement close date: when the billing cycle ends and your statement balance is set
- Payment due date: when that statement balance is due to avoid late fees (and to avoid interest if you are paying the statement balance in full and have a grace period)
In practice, that means:
- You move the money into a dedicated “card payoff” bucket the same day
- You schedule the payment for before the statement closes, or at least before the due date so you do not carry it
If you do not have the cash, call it what it is: new debt. Sometimes necessary, but it should be rare and planned for.
Pick a payoff method you can stick with
Technically, the “best” method is the one you can follow while also funding real life. Two approaches work well:
Debt snowball
Smallest balance first. Best if you need momentum fast. Knocking out a card early can reduce the number of minimum payments, which frees cash and reduces the odds you will swipe again.
Debt avalanche
Highest interest first. Best if your balances are large and you are motivated by math. You save more on interest over time.
Either way: minimums on everything, extra payment to one target card.
One twist: stop reward chasing
Points are not worth it if you are carrying balances. If you are paying interest, rewards are basically a tiny coupon you financed at a high interest rate, often 20% plus.
Make your budget more honest
Credit card dependence often comes from underbudgeting normal life. These categories get people every time:
- Groceries: if you keep running out of food money, bump the line item and cut somewhere else
- Gas and transit: prices fluctuate, your budget should have wiggle room
- Medical and pharmacy: average it out over months instead of pretending it will be zero
- Gifts and social stuff: birthdays still happen even when you are “being good”
- Home and car: small repairs are not emergencies, they are maintenance
Give those categories a realistic number, then plan the rest of your goals around reality. Not around wishful thinking.
To make it stick, add a weekly 10-minute check-in. Look at what you spent, what is coming next week, and which category needs a small adjustment. Consistency beats intensity.
Try a 14-day reset
If you want something concrete to start with, this is a two-week reset that reduces reliance quickly without requiring a total life overhaul.
Days 1 to 2: prep
- List your upcoming essentials for the next 14 days: groceries, gas, meds, key bills
- Choose your spending setup: debit-only week, cash envelopes, or one-card quarantine
- Remove saved cards from online accounts and digital wallets you use for impulse spending
Days 3 to 14: operate on purpose
- Buy only from your planned essentials list
- Track spending once per day for 2 minutes (notes app is fine)
- If you are tempted to swipe, use the 24-hour rule for non-essentials
Day 14: review
- What category ran short first?
- What triggers showed up (stress, boredom, social plans)?
- What one change will make next week easier?
You are building a system, not proving your worth.
Common questions
“My bills are due before payday.”
You likely have a timing problem, not a spending problem. Two options that help:
- Due date changes: some lenders and utilities will move your due date if you call, and many have at least one alternative billing cycle
- Mini buffer: even $200 can help you float timing without swiping
If you are consistently short every month, you may need a deeper budget cut, a higher income, or a temporary hardship plan.
“Should I freeze my cards in ice?”
If you are an impulse swiper, yes, physical barriers can work. Just do not rely on it alone. Remove saved card numbers online, too. Most damage happens with a late-night app purchase, not at a store.
“Should I close my cards?”
Not automatically. Closing a card can reduce your total available credit, which can raise your utilization. It can also affect your credit profile depending on scoring model and how your credit report treats closed accounts over time. If the card is actively harming you, has an annual fee you cannot justify, or you cannot stop using it, closing can be the right call. But for many people, a better first step is to lock it, remove it from your wallet, and keep the account open while you pay it down.
“Is a 0% balance transfer worth it?”
It can be helpful if you have good enough credit to qualify, the transfer fee is reasonable, and you are committed to not adding new charges. The real risk is treating it like a fresh start while the spending habits stay the same. If you do this, pair it with the no-swipe buffer and a non-credit spending setup.
If you are in real trouble
If you are behind on rent, facing shutoffs, considering payday loans, or choosing between food and minimum payments, focus on safety and stability first. Call your utility company and landlord to ask about payment plans. If you are in the U.S., dialing 211 can connect you with local resources. You can also look for a reputable nonprofit credit counselor through the National Foundation for Credit Counseling (NFCC). Getting support is not failure. It is strategy.
A realistic example
Let’s say you have $6,000 on cards and you keep recharging $300 to $500 a month for groceries and gas when cash runs out.
- Month 1: pay minimums, pause extra payments for two paychecks, build a $500 buffer, switch groceries and gas to debit or cash
- Month 2: resume extra payments, keep buffer intact, use cash envelopes for the category you overspend most
- Month 3: increase extra payment by the amount you are no longer accidentally charging, consider snowballing a small balance to free a minimum payment
The win is not perfection. The win is that new charges stop piling on top of old balances.
Final pep talk
When I was deep in debt, I thought the solution was more discipline. What actually changed things was building a setup that did not require daily heroics.
If you take nothing else from this: build a small buffer, make credit inconvenient, and fund your real-life categories honestly. The cycle breaks when your plan matches your life.
Pick one change you can do today, not ten changes you will abandon by Friday. One steady step beats a perfect plan you cannot live with.